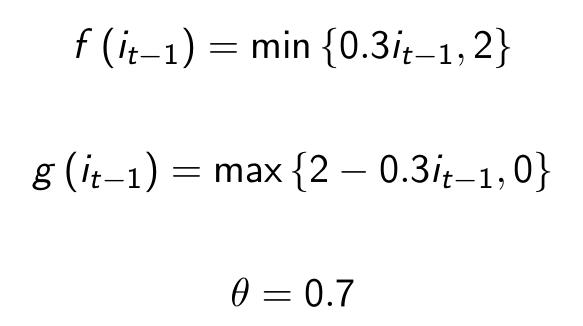Saturday, July 6, 2013

The Role of Financial Institutions

The real world of finance is not populated by the financial traders of model fame. Numerous studies in behavioral economics have identified what appear to be deviations from fully efficient markets with rational individuals. On the individual level, we know that overconfidence leads male traders to trade much more than female traders, and this has a negative effect on their returns. Therefore agents don’t seem to be optimizing -- rather they have their own idiosyncratic, but systematic, biases. On the market level, stock prices seem to exhibit strong short-run momentum while also appear to have long-run mean reverting growth rates. This suggests that there’s something going on with market participants that encourages overshooting in the short run but with corrections in the long run. 

But what has gotten me curious over the past few months is the institutional aspect. In my view, because financial markets are actually populated by institutions that have their own quirks, financial markets can deviate from textbook models in very policy relevant ways.

Most financial models that I have read about are populated by individual investors looking to maximize some expected future consumption stream subject to various constraints. Sometimes these constraints stick to describing feasible budget allocations,and sometimes they also include cognitive biases. But Wall Street doesn't look like this. Traders rarely trade by themselves -- they are usually a part of a large firm. These firms may also have different goals. Some, such as hedge funds, are just in the business of generating pure return whereas others, such as pension funds, are looking to maintain a steady stream of payments to pay out to their customers. Given that these firms have their own institutional demands, this suggests that their trading strategies could be quite different. These structural differences has implications for market efficiency.

Past papers have of course addressed some of these issues. On a within-firm basis, work on the principal-agent problem has shown how compensation schemes can affect fund manager behavior. This would suggest that many financial managers maximize not the utility of the investor, but their payoff in the compensation scheme. Some past work has also indicated that institutional investors, in this case mostly pension funds, do not seem to exhibit the herding and destabilizing behavior that for which they are criticized. However, some of these benign results are being challenged in the recent financial crisis, and this could have major implications for both financial research and monetary policy.

As an example, there have been a set of recent popular articles from the Economist and FT Alphaville on the notion of VAR shocks. VAR is a measure of financial risk that (theoretically) measures the worst case outcome for a firm. For example, a 5% weekly VaR of $5 million means that there should only be a 5% percent chance that the firm will lose more than $5 million over the course of a given week. This typically can be calculated by parameterizing a loss distribution with historical data on volatility and average yields. Even though this measure can mislead by ignoring the amount that would actually be lost in a worst-case outcome its simplicity makes it a natural candidate for institutions to use as a check against overly risky trading strategies. Therefore market moves that can impact the measurement of VAR are natural candidates for making the institutional investors jump.


Pioneering work by Hyun Song Shin, an economist at Princeton, analyzes the role of VAR and argues that it contributes to market procyclicality. Because historical data is used to calculate the VAR that goes into risk weighting, banks may end up levering up their balance sheet just as the business cycle starts to rev up and deleveraging just as the entire cycle comes crashing down. The rising tide of the business cycle makes their VAR look much smaller, therefore allowing them to put smaller risk weights on their assets. Now that the size of risk weighted assets has fallen, banks can play the risk-weighting clause on capital requirements and fund themselves through more debt. This continues until the cycle breaks, at which point VAR measurements are shocked upward by the historical data, forcing a deleveraging in order to meet capital requirements, thereby amplifying negative effects on the business cycle. In particular, this story fits the recent financial crisis very well. Past decades of relative calm made the VAR models docile and ready for the slaughter that was 2008.

I see this as an institutional bug because there’s no efficiency reason why VAR should be used in such a way to risk-weight assets. It does not make for an omniscient Q-measure to identify risk. Rather, VAR is useful because it helps institutions streamline their risk analysis. By doing so, it quite possibly improves an individual firm’s performance by avoiding worse evaluation methods. But with the procyclicality argument made above, it should be clear that a group of banks all using VAR to risk weight their assets end up creating severe negative externalities on the business cycle.

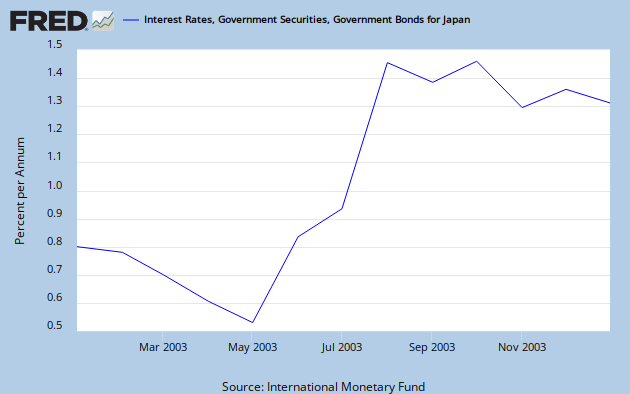
VAR shocks have also popped up in the Japanese case. Back in the 2003 bond yield volatility spike, many Japanese banks ended up selling bonds as the volatility triggered their VAR limits. This intensified the cycle of bond selling until other investors, such as pension funds and insurance companies bought up the bonds and stabilized the market. This serves as another real world example of Shin’s theory that the use of VAR in institutional settings ends up intensifying market volatility.


It should also be clear that the institutional quirks can occur in financial markets with rational arbitrageurs. If the size of institutional flows are large enough, then it may be worthwhile for the smaller traders to just ride the flows to higher returns. There may just not be enough incentive to normalize prices. If the market can stay irrational longer than individuals can stay solvent, then an individual is likely better off to just play along with the market. Given thta we see this kind of serial correlation with hedge funds in the tech bubble, the risk of individuals riding along with the irrationalities of institutions should be taken seriously. In fact, I would go far enough as to argue that the burden of proof is on those who would like to defend their financial models with only individual investors. Given that we know the real world doesn’t work like that, and that this difference can result in dramatically different conclusions, the burden must on the traditionalists to show that models of individual investing can subsume those of institutions in most cases.

To measure these effects and to calibrate new models, attention should be focused on the flow of funds in and out of these institutional investments. This way we could have a better notion of relative size and be able to measure if and how much institutional procyclicality affects markets.

I see two main policy implications of this alternative approach. First, the VAR specific quirks create a further justification for strict capital requirements. Only this way can the risk weighting problem be robustly solved. In terms of monetary policy, a thorough understanding of these institutional quirks can help guide the direction of policy. As monetarism starts to integrate more markets as data points, it becomes more and more important for central bankers to know how to interpret the financial data that comes in. By knowing what’s signal and what’s noise, central banks can better conduct forward looking policy.

In all these examples, we see how institutions -- not individual traders -- can end up driving markets. This marks a departure from traditional finance models in which everybody is just an individual playing the market. It is my hope that this kind of analysis will be useful for understanding causes of market inefficiencies and the optimal framework for financial data in monetary policy.

Thursday, July 4, 2013

Capital Requirements and Nominal GDP Targeting

The Federal Reserve has recently moved to tighten capital requirements for banks, and I see this as a long overdue move. While others have done a very good job summarizing the minutiae of the various ratios, I want to explore what capital requirements really mean and, more importantly, what implications these requirements have on monetary policy.

First, we should be clear on what capital really is. Despite phrases such as “capital cushion” or “holding capital”, capital holdings are not the same as reserves. Capital is meant to describe a type of funding structure, not an asset allocation -- a liability, not an asset. So what is truly at stake here with the capital requirements debate is how banks fund themselves: through equity or debt.

The argument for higher equity funding comes down to reducing the incentive to run on the banks. Because debt liabilities are fixed, creditors are likely to demand their money back at the first sign of trouble. On the other hand, if the funding comes from equity, there is no similar compulsion to run, thereby preventing the fire sale spirals that characterise financial distress.

To visualize this, consider the following bank balance sheet. On the left we have the funding sources -- debt and equity -- and on the right we have the assets. In this first diagram, we see a bank that relies heavily on debt funding (95%) and has very little equity (5%) -- a situation characteristic of many banks today.

Figure 1: Highly Leveraged Bank

If the bank’s assets lose value and drop by a small amount, say 7%, because the debt quantities must stay constant, then all of the equity is wiped out and the bank is left insolvent. On the other hand, had the bank financed itself through mostly equity, then the bank would have stayed solvent and not all the equity would have been wiped out. There would have been less of an incentive to have a run on the debt and, in a time of financial stress, the bank would have avoided a fire sale. These examples illustrate why high levels of debt financing can be so problematic in a system of hard to calculate risks.

Figure 2: Insolvent Bank


Equity funding prevents sudden runs and insolvency. That is the key justification for stricter capital requirements. With this in mind, I now turn my attention to the relationship between these new financial regulations and monetary policy.

The most important relationship between capital requirements and monetary policy is that capital requirements make the financial stability and “reaching for yield” arguments against monetary easing so much weaker. If institutions are well capitalized, what are we scared of? Equity bubbles, like the 2000’s dot com bust, do not leave lasting damage. However, debt bubbles, such as the 2008 financial crisis, can trigger an extended period of deleveraging and general economic malaise. Much as Scott Sumner has recommended, capital requirements can help keep the finance out of macro. While I personally believe insights from the financial literature may reveal more light on the mechanisms of monetary policy, I do agree that the task of monetary policy should stay very separate from that of financial regulation. Monetary policy makers can direct the guidance of interest rates towards maintaining a stable level of nominal output, whereas financial regulators focus on making sure the banks do not fall apart. If institutions are reaching for yield, leave it for regulators to cut the arms off. The monetary authorities need not pay any attention to it.

Even if these capital requirements are not implemented, the mere prospect of them greatly weakens the case for using monetary policy for financial stability purposes by exposing a contradiction: if monetary policy is surgical enough for financial markets, why aren’t capital requirements?

In Jeremy Stein’s February speech on monetary policy and financial stability, he argued that it may be appropriate for monetary policy to prevent bubbles. One of his key justifications was that monetary policy can “[get] in all of the cracks” of financial markets to stamp out bubbles. However, this neglects the bluntness of monetary policy.

In my view, to the extent that interest rates get in all the cracks, they do so by reducing the financial edifice into rubble. But if I am wrong and if monetary policy is indeed precise enough to stamp out bubbles without collateral damage, then aren't capital requirements even more surgical? Indeed, while monetary policy can affect the entire economy’s consumption and investment behavior, the Mogdiliani-Miller theorem suggests that changes in the capital structure would barely have an effect on those macroeconomic aggregates. The greatest irony is that the financial types who support tighter monetary policy to control financial risks are often the same ones who are against stricter capital requirements. But these views are inconsistent. Capital requirements are tailored for financial regulation, and to the extent one supports the blunt use of monetary policy, one should support the strengthening of capital requirements even more.

On the other hand, while capital requirements may make the task of monetary policy easier, some have argued that the reduction in credit from the stronger capital requirements goes against the goal of expansionary monetary policy. First, I do not believe this is true on a purely finance theory basis. As has been discussed elsewhere, higher capital requirements are unlikely to increase funding costs. To the extent that they do raise funding costs, this reflects an efficient reduction in the government’s implicit subsidies for bank debt. Second, even if this were the case, we should remember that monetary policy is not credit policy. If there is a reduction in credit, the question for the monetary authorities is whether this reduces nominal GDP. Depending on that, the Fed should ease or tighten. Therefore, a well functioning monetary policy should fully offset the potential impact of credit shocks. The level of credit in an economy is a matter of financial organization, something far outside the domain of monetary policy. The Fed should adjust the path of interest rates depending on where they want to see nominal GDP go.

While the above discussions focus on how capital requirements make monetary policy easier, I also believe better monetary policy, especially through a nominal GDP target, can help make capital requirements simpler. It’s useful to remember that debt is an extremely important channel through which nominal shocks have real effects. Rarely are these bonds written with inflation indexing, so stabilizing nominal aggregates can help make satisfying capital requirements easier. Under a nominal GDP target, the size of the debt chunk of the balance sheet can stay roughly around the same level as the size of the equity chunk, reducing the amount of scrambling that can occur in financial markets as bank struggle to reach their regulatory goals.

To conclude, I should note that there is an elegance in the combination of nominal GDP targeting, a robust monetary policy regime, and high capital requirements, a robust financial regulatory regime. As Plosser recently noted:

In the context of monetary policy, I have long advocated simple, robust rules and transparent communications.2 Robust rules are important because they are intended to work well in a variety of environments. This reflects our limited knowledge about the true determinants of economic outcomes. Economists have also come to understand that using policies that are optimal in one specific economic model can often deliver very poor outcomes if that model proves incorrect. So a policy rule that operates well under a wide range of models is a better and more robust approach.
The same approach applies to the design of regulatory frameworks as well. Because the financial world is very complex, there is merit in simple, transparent regulatory solutions designed to work reasonably well in a wide range of situations. We want rules that regulators can enforce without having superhuman knowledge or foresight. However, we can predict with virtual certainty that private actors will seek to evade regulatory restrictions and taxes. This is often called "regulatory arbitrage." We also know that enforcement costs rise as firms' incentives to evade regulations increase.
In my view, simple mechanisms that are harder to evade — and even better, mechanisms that utilize market forces to discipline firm behavior — are superior to an elaborate list of rules that seeks to cover every possible outcome. Simple and transparent regulatory mechanisms make it easier for market participants to predict how regulators are likely to behave. This, in turn, makes it easier for regulators to credibly commit to implementing the regulations in a consistent manner.
Reading Plosser’s second and third paragraphs really shines light on some common issues such as commitment, credibility, and transparency that relate financial and monetary policy. For monetary policy, these qualities can help guide the expectations that give monetary policy its oomph. For financial regulation, these qualities limit the hidden fault lines that can make crises so severe. One can only hope that policy can combine these all these qualities to make a more enlightened monetary and regulatory framework.

Man of Steel: Morality as an Evolutionary Advantage


"Your sense of morality is an evolutionary disadvantage...and evolution always wins"

This post will not be about monetary policy -- it will barely be about economics. But nonetheless, after seeing Man of Steel, I thought a fun essay connecting some core concepts from game theory and our notions of morality are in order.  While none of the insights are particularly new, the specific application to Man of Steel should be, and I hope you enjoy.

The core proposition was the one uttered by the evil Kryptonian woman pictured above. Between high paced punches and knocking helicopters out of the sky, Faora-Ul uttered to Superman: “Your sense of morality is an evolutionary disadvantage...and evolution always wins.” Whether evolution always wins is an issue that I will attend to perhaps on a different occasion, but I want to address the first claim. Is a sense of morality antithetical to the survival of the fittest?

With what we know about animal behavior, the answer seems to be a resounding “no”. While it is difficult, if not impossible, to impose a natural system of morality for animals, I think a natural interpretation could be the presence of behaviors that may not be beneficial to oneself. While morality surely goes beyond self-flagellation, it does serve as a useful residual for explaining altruistic actions.

One of the most commonly evoked examples of such behavior in the animal kingdom comes from ground squirrels. These squirrels make sure to loudly alarm their kin mates of the presence of dangerous predators. On the squirrel level, this is very costly behavior because it increases the risk that a predator finds and eats the squirrel. Yet if all squirrels do this, everybody is better off. This is a classic example of the difficulty of providing public goods, as every squirrel has the incentive to free-ride off of the alarm calls of others. But if nobody makes the alarm call, then they are all at a higher risk of being eaten by an eagle. Somehow, the squirrels manage to overcome this public goods problem. There’s no Coase theorem contract, no government enforcement, yet squirrels provide the public alarm nonetheless.

Why? In this case it’s simple: kin selection. Because these ground squirrels usually spend most of their lives around family, it’s in their incentive to protect their peers in order to pass on the most amount of genes to the next generation. Under the framing of Richard Dawkin, the selflessness of the individual squirrels comes from the selfishness of a gene that may encourage the alarm calls. To see this logic, suppose there exists a squirrel with a gene that induces the alarm calls. Then his offspring are also likely to have the same gene. Because the alarm behavior serves to preserve his offspring, then this alarm gene will propagate its way through the population. Therefore, this gene selfishly works to propagate itself, even at the cost of its host squirrel. Such is the power of family.

The above explanation has an interesting analogue from public economics, in particular the analysis of firm mergers in the presence of positive externalities. For example, consider the case of two stores that need to decide on their advertising budgets. Because of their proximity, the stores are complementary in the sense that more traffic in one store means more traffic in the other. Therefore in equilibrium, if there is no cooperation, these firms will choose an inefficiently low level of advertisements because they fail to take into account the positive benefits their own ads have on the other firm. But if they merge, the merged firm can capture this positive externality. While this may seem contrived, you can think of family structure as a merger between individual squirrels. By the same logic, this genetic merger allows the family to capture the positive externality from the alarm.

One of the greatest appeals of this kin selection theory is that it yields many good out of sample predictions. The original evidence was just the basic anomaly that the squirrels would take any kind of altruistic behavior. But by extending the gene logic, then it should be the case that the probability of any given squirrel to sound the alarm is positively related to the extent of familial relations between the squirrel and the group. Indeed this is the case, as the females, who tend to spend their lives around the same family, are much more likely to sound the alarm than the males, who go off to live with other squirrel groups in adulthood. These females are also more likely to sound the alarm when they are around close relatives -- further corroborating the kin selection hypothesis.

From this relatively scientific evolutionary analysis of animals I now pivot to the much more speculative and unscientific theorizing about human systems of morality. Here, I will push the claim that systems of human morality were also driven by similar evolutionary principles, and that this framing of morality helps explain some of the universality in basic morality across societies.

Again, let’s consider a concrete example. Consider the commandment “Thou shalt not covet thy neighbor’s wife”, and consider the most literal interpretation of it. Indeed, I do believe such a rejection of wife-stealing is fairly universal. Even in polygamous societies, I do not believe relations with a woman who is somebody else’s wife are encouraged. What could be a game theoretic interpretation of this? Well, suppose men indeed were encouraged to chase after the wives of others. What would the equilibrium be? If the “cheating” status of partners in a relationship were to be private information, then there could be an adverse selection spiral in which men do not believe their wives are faithful, and then wives, because they are not being treated as well, end up being open to extra-marital affairs. Therefore, society as a whole converges on the norm that a neighbor’s wife should not be coveted in order to avoid the bad adverse selection equilibrium.

I snuck in a few tricks into the past paragraph. First, what I described was more characteristic of group selection, and not kin selection as with the squirrels. Group selection is much more controversial due to its tenuous connection with the empirics and its use as a justification for genocide. Nonetheless, I do believe it provides a parsimonious framework for some of these game theoretic justifications for moral norms. Second, it should not surprise us that many observed societies do have these kinds of norms. Since societies that do not have this norm end up spiralling into some bad equilibrium, they end up erased from the historical record. As a result, we only see the societies that succeeded and, surprise, they tend to exhibit these norms that avoid bad equilibria.

Those familiar with philosophy will be able to identify my above analysis with the Kantian notion of a categorical imperative, or that ethics should be based on rules that everyone can apply. Indeed, a game theoretic interpretation of a stable equilibrium captures this notion. The stable equilibrium is the one where everyone can play the same strategy of not violating a moral code. This is why potential alternative moral rules, such as “do not covet thy neighbor’s wife except if she is very fertile and attractive” cannot hold. They cannot be held symmetrically, and therefore fail to propagate themselves through a group.

While the above analysis does not qualify as scientific (it’s quite hard to falsify), I do believe it’s a nice economic interpretation for why moral structures can be so similar across societies. Most historical codes -- I am thinking all the way back to Hammurabi’s -- have similar core ideas: don’t steal, don’t kill, etc. One would think that through the thousands of years of history, there must have existed at least one society that had very loose rules regarding murder and theft. Yet I would claim that we do not hear of these societies because the loose rules caused the society to collapse before we could find evidence for them.

As a final example, consider again the Kryptonians mentioned in Man of Steel. If the moral structure of the old Kryptonian society was governed by Faora’s preference for no regard for organisms of other species, it seems highly unlikely that they would have been able to persist for so many thousands of years. First, on a planet-level basis, would it have taken that long before military coups pulled the Kryptonian people apart? Given how easy it is for our Congress to disagree, there must have existed at least one disagreement about how to treat organisms of different species in the hundred thousand years of glorious expansion. Moreover, such a cold moral system against other organisms would have cut the Kryptonians off from the most important driver of prosperity: trade. With these weakness, it seems more likely that they would have been conquered or merged into another society that exhibited more robust morals against mass exterminations of other races.

These economic interpretations add a new spin on the design of moral structures. By grounding the development of morality in a game theoretic framework, I can derive a very natural reason why certain moral rules are so universal. So rest assured, humanity . In spite of what the villains from Man of Steel may have us think morality is an evolutionary advantage, and more evolved humans will not be forced to leave it behind.

Sunday, June 30, 2013

Why Nominal GDP Targeting Solves the Credibility Problem

Monetary easing at the zero lower bound seems to work in practice. But does it work in theory?

In his recent BIS speech, Rajan argues that monetary policy at the zero lower bound requires an impossible commitment. For the Fed to get real rates low enough for the economy to "lift-off", the only option is to raise expectations of future inflation. But what happens when that future arrives? Now that the economy has escaped the zero lower bound, the Fed is tempted to renege and stick to the original inflation target. Market participants, knowing this, then refuse to believe the original commitment, leaving the Fed stuck.

The same argument was made in reverse to explain why the Fed could not escape the high inflation equilibrium of the 1970's. As argued by Barro and Gordon, the Fed declares that it wants low inflation. If this is credible, then agents lower their expectations of inflation. However, this tempts the Fed into actually delivering high inflation to exploit the Philips curve relation and lower unemployment. As a result, the Fed is stuck at high inflation.

But the Fed escaped. The last release of the PCE price index came in at just 1.0% year over year, suggests that, if anything, the Fed lowered inflation too much. How did policy do this? In the case of moving from high inflation to low inflation, the solution was simple: adopt an inflation target. If the Fed only has to keep inflation from deviating from a target, then of course it will not cheat with any kind of surprise inflation. This kind of target can also be self reinforcing through a reputation mechanism, as the Fed knows that if it cheats now it will hurt more in the future. This removes the temptation to renege as unemployment deviations no longer matter. In the end, the Fed was successful. It managed to lower inflation from around 8% in the 1970's to the 2% levels we see today.

The target is just as important today. If the entire goal is to keep inflation at 2%, then of course there can be no commitment to forward guidance! But that is a criticism of inflation targeting, not forward guidance. Therefore the Fed needs to change its policy target. If the Fed decides its operating procedure no longer is to keep inflation at 2%, but rather to keep nominal GDP on a 5% trend, this drastically changes the perception of what is credible. The Fed no longer needs to "credibly promise to be irresponsible" -- it can just change the definition of responsibility.

If it seems magical that the Fed can change this definition so easily, it's because the loss functions that underpin these models of time inconsistency are arbitrary. In the Barro and Gordon case, the reason low inflation was time inconsistent was because unemployment deviations were included. Once the Fed ignored unemployment, its actions were time consistent. In the current forward guidance case, the reason high inflation is inconsistent is because the inflation rate is in the loss function. Therefore replacing inflation with a nominal GDP term would solve the time inconsistency problem now. The Fed gets to determine these costs. With the right loss function, credible policy becomes almost obvious.

The government can take steps towards this in many different ways. On the Fed side, they could come out with announcements saying that they are more concerned about stabilizing certain level variables -- for example nominal GDP. This would show that the Fed's loss function is changing, and therefore the expected policy adjusts. On the congressional side, they could pass a law that defines the dual mandate in terms of a nominal GDP target. This institutional reform would make Fed commitments to low future rates credible and help pull them out of the zero lower bound.

When nominal GDP targeting is cast as a framework for making future paths of interest rates credible, the implementation details of a nominal GDP target also become self evident. It's no longer a "whatever it takes" target, rather it becomes a template for adjusting the nominal interest rate. Raise the policy rate if nominal GDP is above trend, lower the rate if it's below. And if nominal GDP is so far below trend that your interest rate is stuck at zero, then provide forward guidance that the interest rate will be at zero until nominal GDP normalizes. Even though this is about future policy, there is no commitment problem. The promise is already optimal.

Therefore, nominal GDP target can make policy on the monetary instrument even more rule based. A well-defined target may make unconventional policies such as quantitative easing unnecessary -- forward guidance would be able to deliver similar results. As evidence, the recent whispers of Fed tapering have shown up most strongly in the forecasts of future interest rates. While this might seem peculiar because the Fed has not said anything about future rates, it is natural if QE is seen as a signal of the Fed's stance on future rates. Gavyn Davies notes:
There is evidence that this signalling effect of Fed balance sheet changes might be very powerful. If the Fed is not willing to “put its money where its mouth is” by buying bonds, then the market might take its promises to hold short rates at zero less seriously than before. According to this recent research by the San Francisco Fed, it is possible that a sizeable proportion of the total effect of QE on bond yields came from these signalling effects rather than the portfolio balance effects which have usually been emphasised by the central banks.
If this is the case, then the credibility effect of a nominal GDP target on forward guidance would be enough. Long rates across the board -- MBS, treasury, corporate debt -- could be lowered merely by the expected future path of rates without direct Fed intervention into those markets. Note that because inflation targeting would suffer from credibility issues when it comes to forward guidance, it can get stuck with a persistently negative output gap. This may end up forcing policy makers to deviate from the rule. So surprisingly, nominal GDP targeting would actually be more rule-based as a result.

Credibility is no problem at the zero lower bound. A nominal GDP target would go a long ways towards securing it -- in both practice and theory.

Monday, June 17, 2013

Rate Dependent Taylor Rules

Jean Blanchard, the head of the IMF, described pre-crisis monetary policy as having "one target, inflation, and one instrument, the policy rate." This policy rate was also not to be adjusted at will. Rather, it was to be guided by a Taylor Rule. However, this policy resulted in perverse outcomes at the worst of times. Even after the sale of Merrill Lynch and the collapse of Lehman, inflation targeting allowed commodity shocks to hold the Fed back from aggressive policy.

This failure among others has led many to view nominal GDP as the new target of choice. But as we have this new conversation, we should not forget about how to change our approach to the instrument. In particular, to what extent does the Taylor Rule still matter? In this post, I will argue that the Taylor Rule can actually be a powerful template for better policy. By modifying the Taylor Rule to be sensitive to the absolute level of the interest rate, the Fed would have a flexible yet robust policy regime that effectively harness the most important tool of monetary policy: expectations.

Section 1 reviews the concept of the Taylor Rule, Section 2 discusses the modification, Section 3 compares the new rule with the historical data, Section 4 connects the new rule to other policy proposals, and Section 5 concludes.

1. Introduction

The principle behind the Taylor rule is to adjust the short term interest rate based on inflation and the output gap. The original rule from John Taylor's 1993 article is:


Where r is the short term nominal interest rate, Ï€ is the rate of inflation over the past year, and y is the percent deviation of real GDP from its trend. From a positive perspective, this simple rule fits past Fed policy quite well. From a normative perspective, its clear description of what monetary policy was during the good times can hopefully give us better guidance on what monetary policy should be during the bad.

The Taylor Rule, because it is so simple, also helps with setting a rule-based policy. There is a long literature on the differences between discretionary and systematic policy, and the general conclusion is that systematic policy, because it can shape expectations of future inflation, is more effective at stabilizing the economy. The Taylor Rule is systematic because it is a transparent rule. This allows the central bank to shape expectations of how the Fed will act. As a result, the central bank provides markets with more certainty over the future path of economic growth.

While the coefficients are merely rules of thumb, one important note is that the coefficient on inflation should be greater than 1. This is known as the Taylor Principle. It is because real, not nominal, interest rates drive inflation. Therefore, the nominal interest rate needs to rise by more than 1% for every 1% increase in inflation to stabilize inflation. This is a good rule for most times, although down below I will argue that there are better options for low interest rate environments.

2. A Rate Dependent Taylor Rule

2.1 Motivation

A limitation of the traditional Taylor Rule is that the coefficients are constant across all values of the interest rate, inflation, and the output gap. However, the relative costs of inflation and output gaps change depending on the interest rate. When interest rates are very low, inflation has the collateral benefit of helping the central bank avoid (potentially self-imposed) policy difficulties at the zero lower bound. On the other hand, if interest rates are already very high, excessive inflation merely adds to economic uncertainty.

Therefore, the weights on the Taylor Rule should not be identical in all states of nature. Rather, because the relative costs of inflation and output gaps change depending on the interest rate, the Taylor Rule coefficients should also adjust.

This makes debates over particular coefficients quite silly. Instead of arguing over whether the output gap should have a coefficient of 0.5 or 1, the question should be how to systematically adjust those coefficients.

For example, when Nikolsko-Rzhevskyy and Papell evaluate whether Taylor Rules should justify Quantitative Easing, they conclude that a proper Taylor Rule would not. Although a Taylor Rule that heavily weights the output gap may justify QE, they argue the rule should be rejected because it would not have been hawkish enough on inflation in the 1970's. However, this implicitly assumes that policy makers cannot vary their weights on output and inflation over time. But if these changing weights can be specified in a transparent rule, then it's very likely that the optimal rule would involve both strict tightening in the 1970's and aggressive easing right now.

2.2 Specification

With the traditional rule in mind, I now propose an alternative that I call the Rate Dependent Taylor Rule. In this rule, set the instantaneous target (v) at


For some functions f and g that are weakly increasing and decreasing in the interest rate, respectively. Then set the actual rate as a weighted average of the interest rate last period and the current instantaneous target


For some θ between 0 and 1.

Therefore, a particular specification could be:


These response coefficients are plotted in the following chart. Observe that at the black line when the interest rate is 5, the two Rate Dependent coefficients match the traditional Taylor Rule.


There are three key design features of this specification.

First, the values of these coefficients are fixed in the range between 0 and 2. The logic behind this is to prevent excessive volatility in the interest rate. With these bounds, we also have justification for the slopes of 0.3. Recall that for the original rule, the coefficient on inflation was fixed at 1.5 and the coefficient on the output gap was fixed at 0.5. The modified rule takes on these values only if the interest rate is 5, the historical average of the federal funds rate. Therefore, the modified rule can both be more hawkish and more dovish than the original Taylor rule, contingent on economic conditions. This way, the modified Taylor rule can emulate the magnitude and volatility of the old Taylor rule, but also provide additional flexibility.

Second, when the interest rate is below 3.3, the example above actually violates the Taylor principle. This is no accident. Recall that the logic of the Taylor principle was to allow the central bank to keep a lid on inflation by ensuring that the real rate rises in response to inflation. But if interest rates are already at the low level of 2%, we actually want to encourage inflation so that the nominal rate can stay at the 5% level. Intuitively, this strengthens the negative feedback loop that keeps the nominal interest rate around 5%, giving the central bank more room to operate. 

Third, the interest rate is highly persistent. This is an issue discussed at length in Woodford's work "Optimal Monetary Policy Inertia", and there are two main justifications.

On one hand, excessive interest rate volatility can itself be harmful as agents spend more resources trying to avoid holding money. This is the argument for a Friedman rule for zero nominal interest rates, and although the argument is not as strong in the case, the logic still applies. High nominal rates can be distortionary, and thus their variance should be limited.

Moreover, without persistence it is hard for central banks to signal commitment to future interest rate paths. Future policy would be more unpredictable. Because the rate can change dramatically in response to new conditions, the Fed would not have a framework for commitment. Because one of the key selling points of a Taylor rule is to help guide expectations, to have an instrument that responds too quickly to economic conditions weakens the expectations channel. Therefore, the instrument should be persistent. In my rule, I choose a value of 0.7, which is very close to the value of 0.65 cited by Woodford.

3. Historical Comparisons

This specification is first compared against the traditional Taylor Rule and actual federal funds rate during the Great Moderation and up to the current period. Note that this isn't really a policy simulation. In fact the parameters that are rate dependent look at the actual federal funds rate in the previous period, not the rate-dependent rate. Therefore, this version gives a better picture of how the policy would give advice at each moment in time. In the future, I intend to further investigate the dynamics.


In the top panel are the various interest rates and rules. The red line is the actual effective Fed Funds rate, the gold line is the traditional Taylor Rule, and the green line is the Rate Dependent rule. The panel suggests that this interest rate rule actually fits monetary policy in the Great Moderation very well. In particular, comparing the traditional Taylor Rule with the Rate Dependent rule in the 2003-2007 period suggests that low interest rates may have been the justification for the downward deviation in the Taylor Rule.

The bottom panel shows a running time series with the coefficients in front of inflation (blue) and output gaps (magenta) changing over time. This shows that although the traditional Taylor Rule matches the policy advice of the Rate Dependent rule for the second half of the 1990's, in general they do not always correspond.

Another historical period of interest is the 1970's and 80's. In this time, inflation was far too high. Therefore, an effective rule should call for more hawkish policy. Indeed, the Rate Dependent rule does that. It would have called for interest rates in the 1970's and 1980's to be up to 10 percentage points higher than they actually were, and approximately five percent higher than what the traditional Taylor rule would have called for.

This is similar to what Evan Soltas noted about how a nominal GDP target would have called for tighter policy in the 70's. Even though the Rate Dependent rule would at times call for easier policy to stabilize output, it  is very hawkish when inflation is high. As such, it would still anchor inflation expectations with the promise of disciplined policy when inflation and the Fischer effect push up interest rates in the future.


4. Relationship with Forward Guidance, Nominal GDP Targeting, and a Virtual Fed Funds Rate

Although the Rate Dependent rule fits the historical data quite well, there is one large deviation. In the current environment, the rule says that the Fed should be easing. Hard. While the zero lower bound constrains the Fed from actually hitting the rate advocated by this rule, this does not mean the rule cannot help guide policy. In fact, the greatest appeal of the Rate Dependent rule at the current juncture would be its justification for forward guidance. If the large gap can't be closed with current short term rates, then perhaps it can be filled with future ones.

A Rate Dependent rule frames the current tightness in monetary policy by identifying a large deviations from a rule that fits the historical data. While this method may not be ideal, it shows how even the traditional framework of seeing monetary policy through instrument rules justifies aggressive easing at this juncture. 

Moreover, the theoretical reasoning behind the Rate Dependent rule is much more familiar for those who think in terms of Taylor Rules. Unlike a nominal aggregate target, the Rate Dependent rule is a concrete policy that can be implemented. It helps to assuage the concerns of John Taylor when he complains that an open ended nominal GDP target fails to give "quantitative operational guidance about what the central bank should do with the instruments." This way, the Rate Dependent rule helps to justify additional easing to a broader audience.

This alternate framing also gets around potential credibility issues nominal GDP targeting. This is not to say a nominal GDP target would  not be desirable but a 2012 Dallas Fed paper did bring up some credibility issues with such a target.  Evan Koenig, the vice president of the Dallas Fed, pointed out that the Fed does not have a good record of stabilizing nominal GDP growth. A graph from the paper is reproduced below. 


However, the historical comparisons above clearly show that the Rate Dependent rule is a good description of historical policy. Moreover the scatter plot below clearly shows that the Rate Dependent rule is also a good predictor of what a nominal GDP target would require. Therefore, the Fed can point to this rule and do a monetary two-step. While the Fed foxtrots into a more enlightened nominal GDP target, it can still maintain and demonstrate its credibility to this new policy path by justifying it with the historical experience.


The Rate Dependent rule is also a close cousin of the virtual Federal Funds rate, as advocated by my colleague Miles Kimball. In fact, the two proposals complement each other since the Rate Dependent rule provides a systematic approach for determining the virtual rate. This way, the Fed doesn't just ease when it "feels that monetary policy should be more expansionary." It would ease when it could point to the rule and say that it must.

5. Concluding Remarks

Of course, there is much work yet to be done. The above analysis is very descriptive and requires more formal modeling. In an upcoming post, I intend to discuss more about dynamics and the persistence of this rule. Doing more case study analyses of the rule in historical contexts would also be useful.

Much of the recent push for nominal GDP targets has neglected rules for the instrument. This omission runs the danger of confusion over the steps that need to be taken when a "whatever it takes" policy is declared. The Rate Dependent rule cuts through that confusion. It combines the rule based approach characteristic of traditional Taylor Rules with the recognition that the costs of inflation or output gaps can depend on the interest rate. In bridging various intellectual cousins, this policy forms a stronger basis for monetary easing now, while also committing to smart hawkishness later.

Friday, June 14, 2013

When the Zero Bound Didn't Bind


The zero lower bound didn't always bind. For three months after Lehman's collapse on September 15, 2008, the federal funds rate stayed above zero. In this period of time, the Fed managed to provide extensive dollar swaps for foreign central banks, institute a policy of interest on excess reserves, and kick off the first round of Quantitative Easing with $700 billion dollars of agency mortgage backed securities. Finally, on December 15, 2008, the Fed decided to lower the target federal funds rate to zero.

It is important to remember the sequence of these events. It is easy to think that the downward pressure on interest rates was the inevitable consequence of financial troubles. Yet the top graphic clearly contradicts this. Each of the dotted lines represents a FOMC meeting, and each of these meetings was an opportunity for monetary policy to fight back against the collapsing economy. The Fed's sluggishness to act is even more peculiar given that there were already serious concerns about economic distress in late 2007. As, the decision to wait three months to lower interest rates to zero was a conscious one, and one that helped to precipitate the single largest quarterly drop in nominal GDP in postwar history. The chaos in the markets did not cause monetary policy to lose control. Rather, the Fed's own monetary policy errors forced it up against the zero lower bound.

This is not to say those mistakes were purposeful. But in the high stakes game of central banking, even benign neglect can be dangerous. These failures in the last three months of 2008 can teach us many lessons about what should be done for future monetary policy. Only this way can we be more sure that careless mistakes won't jeopardize the future path of monetary policy.

One of the first steps would be to switch to a nominal GDP target. This would have two primary effects.

First, while this by itself is not a concrete instrument, it would be an important step in giving policy makers more freedom in responding to crises. Our current focus on inflation can cause particularly perverse outcomes when the economy comes under stress. During the September FOMC meeting right after the Lehman collapse and the Merill Lynch merger, in spite of the chaos in financial markets, the Fed chose to leave interest rates unchanged because of concerns about commodity price inflation. After such a long period of worrying economic conditions, the Fed choked because of a relative price change that was beyond the control of monetary policy to tame. A nominal GDP target would be robust to these kinds of shocks and better keep policy on track during the unfolding of a crisis.

Second, a nominal GDP target would also make policy after interest rates hit zero more credible.When the Fed is at the zero lower bound, one of the most important policy levers it has left is to adjust expectations of future interest rates. This is known as forward guidance, and is a consistent theme in the literature. In Krugman's original work on Japan's liquidity trap, he termed this kind of policy "credibly promising to be irresponsible". If this sounds peculiar, you are not alone. John Cochrane observes that
the key to stimulus when interest rates are zero is for the Fed to commit to keeping interest rates low, lower than than we and the Fed know it will want them to be when the time comes.
As a result, the Fed has a hard time committing to its forward guidance because it will want to renege in the future. However, if there were a nominal GDP target, this would remove the pressure to renege. In a sense, declaring a nominal GDP target changes perceptions of what the Fed wants.  By making policy systematic, and not discretionary, we can actually shape expectations and make the current policies of forward guidance and quantitative easing that much more effective.

Tuesday, June 4, 2013

For Sussing Out Whether Debt Affects Future Growth, the Key is Carefully Taking into Account Past Growth


On Miles' website we have a companion post to the previous post on an instrumental variables analysis of the RR dataset. In the companion post, we walk through more of the regressions and illustrate how controlling for past growth can erase almost any effect of debt on future growth. The core conclusion?
The two of us could not find even a shred of evidence in the Reinhart and Rogoff data for a negative effect of government debt on growth for either growth either in the short run (the next five years) or in the long run (as indicated by growth from five to ten years later).
Even though the estimated slopes are still small, we also discuss why this difference -- between small negative and small positive numbers -- matters for policy. For more, be sure to read the full post here.